Can You Get a Payday Loan With an ITIN Number?
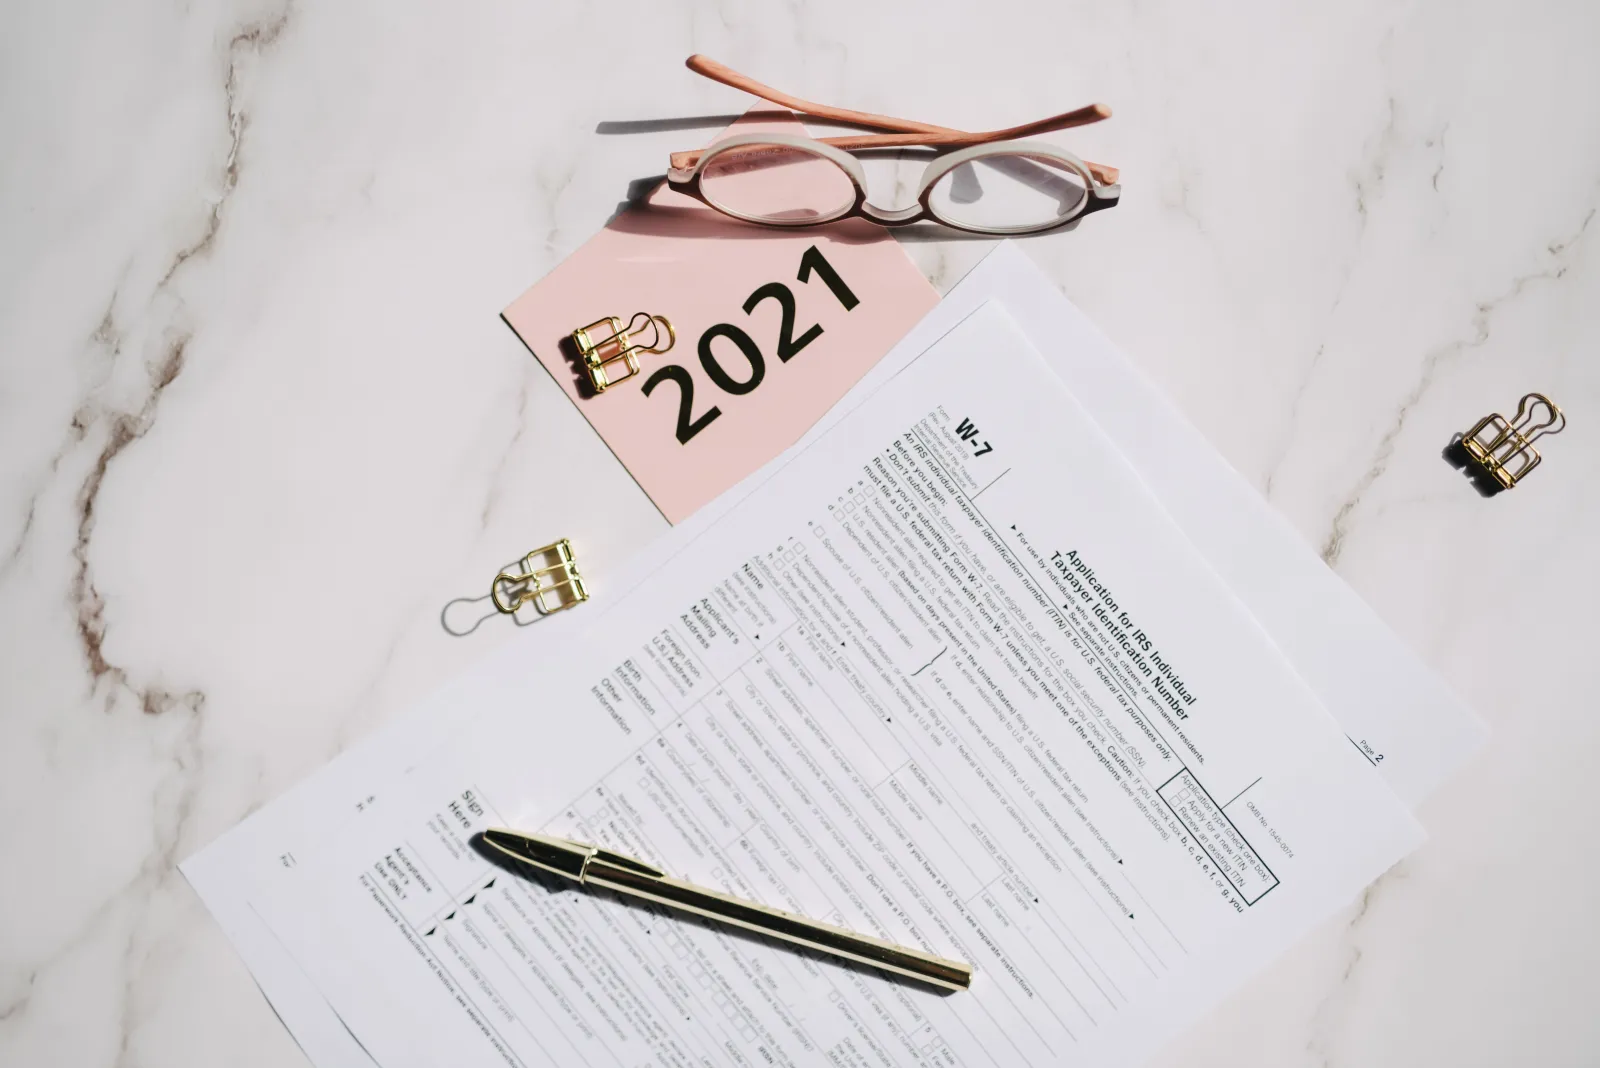
Sometimes. Whether you can get a payday loan with an ITIN instead of a Social Security number depends on the lender and on your state. An ITIN is a real U.S. taxpayer identification number, but each lender decides which ID numbers it accepts, and some states make lenders check every loan in a database. Payday loans are also not available everywhere. By our count of verified state rules, Georgia makes payday lending unlawful, Arizona and the District of Columbia no longer license payday lenders, the regulators in West Virginia and Hawaii say payday loans are prohibited there, and 15 more states cap rates at a level where we list no payday stores.
What an ITIN is, and what it is not
An ITIN (Individual Taxpayer Identification Number) is a 9-digit number the IRS issues to people who need a U.S. taxpayer number for federal taxes but are not eligible for a Social Security number. The IRS issues ITINs regardless of immigration status.
The IRS is also clear about what an ITIN does not do. It does not:
- authorize you to work in the U.S.,
- provide or change immigration status,
- qualify you for Social Security benefits, or
- serve as identification outside the federal tax system.
That last point matters for borrowing. A lender may still choose to accept an ITIN as your taxpayer number, but no rule makes the ITIN itself a form of ID. You will usually need a photo ID as well.
How payday lenders decide which numbers to accept
The Consumer Financial Protection Bureau (CFPB) describes a payday loan as a short-term, high-cost loan. It is generally for $500 or less and is typically due on your next payday. Lenders usually ask you to authorize repayment, either with a post-dated check or by letting them debit your bank account.
Which taxpayer number a payday lender accepts is mostly the lender's own policy. Some ask for a Social Security number and stop there. Others accept an ITIN. Policies can differ between a lender's stores and its website, so the only reliable answer comes from the lender itself.
Two federal rules shape what you can expect:
- Lenders may ask about immigration status. Under Regulation B, which carries out the Equal Credit Opportunity Act, a creditor may consider your immigration status (12 CFR 1002.6(b)(7)). It may also ask for other facts it needs to know how it can get repaid.
- Lenders may not consider national origin. The same rule says a creditor may not consider race, color, religion, national origin or sex in any part of a credit transaction (12 CFR 1002.6(b)(9)). Being asked about status is allowed. Being turned down because of the country you come from is not.
The bank account question
Because repayment usually comes from a checking account, you will usually need one. Banks and credit unions follow a federal customer identification rule (31 CFR 1020.220). For a person who is not a U.S. person, it lets them use one of these numbers: a taxpayer identification number (which can be an ITIN), a passport number and country, an alien identification card number, or the number of another government photo ID that shows nationality or residence. Each bank still sets its own account policy, so ask which of these it accepts.
No Social Security number at all?
If you have no Social Security number, the ITIN is the federal taxpayer number made for your situation. The IRS issues it to people who need a U.S. taxpayer number for federal taxes but are not eligible for a Social Security number. You apply by mail or in person with Form W-7, and the IRS says to include your tax return in the application package. Getting an ITIN is a tax step, not a way to qualify for a loan, so apply only if you have a federal tax reason to.
If you have neither number, some options do not depend on one:
- A bank or credit union account. The federal customer identification rule lets banks and credit unions identify a person who is not a U.S. person with a passport number, an alien identification card number or another government photo ID, not only a taxpayer number (31 CFR 1020.220). Each one sets its own policy.
- A pawn loan. You leave an item with a licensed pawn shop and borrow against it. In Texas, for example, a pawnshop needs a state license, a pawn loan matures in one month unless both sides agree in writing to extend it, the shop must hold an unredeemed item for at least 30 more days, and you are not required to redeem the item: if you do not, the shop keeps it (Tex. Fin. Code §§ 371.051, 371.160, 371.169, 371.170). Rules differ by state; see Texas pawn shops or your state's page.
- Help that is not a loan. 211 can point you to local help with rent, utilities and food.
Be careful with online offers that promise a loan with no number and no checks at all. Check that the lender holds a license in your state, which our lender directory shows by state.
What you'll need
Requirements differ by lender and state. Payday lenders often ask for:
- Your ITIN letter from the IRS (the CP565 notice), if the lender accepts an ITIN in place of a Social Security number.
- A photo ID. Which IDs count, such as a passport, a state ID or a consular ID, is up to the lender.
- An open checking account in your name, plus recent bank statements. Repayment is usually drawn from this account.
- Proof of regular income, such as pay stubs or bank deposits.
- A phone number and current address.
Ask the lender which documents it accepts before you go. If you want to ask a store in person, our lenders near me page lists licensed stores with phone numbers and hours.
State rules that can matter
Some states require payday lenders to check a statewide database before every loan, to enforce limits on how many loans you can have. A database needs a way to identify you. In Florida, the statute lists what the lender must submit before each loan: the borrower's name, "social security number or employment authorization alien number," address, driver license number and loan details (Fla. Stat. § 560.404(24)(a)). That list does not mention an ITIN. The state's rules can add details, so ask a Florida lender directly how it handles this.
| State | What the rule says | Law |
|---|---|---|
| Florida | Every payday lender must check a statewide database run by the Office of Financial Regulation before each loan. | Fla. Stat. § 560.404(24)(a) |
| Virginia | Before a short-term loan, the lender must check a real-time loan database and report each new loan and payoff that day. | Va. Code Ann. § 6.2-1810(B) |
| Washington | Lenders use the Department of Financial Institutions' database to check your outstanding loans and eligibility. | Wash. Rev. Code § 31.45.093 |
| South Carolina | Lenders must check a common real-time database before each transaction. | S.C. Code Ann. § 34-39-175(A) |
| Georgia | Payday lending is illegal. Loans of $3,000 or less are unlawful unless made under an exempt law, such as by a bank, credit union or installment lender. | O.C.G.A. § 16-17-2 |
| Arizona | The payday lending law expired on June 30, 2010, and the state no longer licenses payday lenders. | Former A.R.S. §§ 6-1251 to 6-1263; DIFI FAQ |
| District of Columbia | The District no longer authorizes payday (deferred deposit) loans by check cashers. Other small loans are held to a 24% a year interest cap. | D.C. Code § 26-319(b) |
From our state rules data, last checked October 9, 2026. Rules change. Check your state's page in the lender directory.
Where payday loans are not available
Following each state's own law, by our verified state rules:
- Prohibited: Georgia, where making, offering or arranging loans of $3,000 or less is unlawful unless the lender operates under an exempt law (O.C.G.A. § 16-17-2).
- No longer licensed: Arizona (its payday law expired on June 30, 2010) and the District of Columbia (deferred deposit was repealed in 2007, D.C. Code § 26-319(b)).
- Prohibited, according to the state regulator: West Virginia, whose Division of Financial Institutions says "Traditional 'Payday Lenders' are generally prohibited within this state," and Hawaii, whose Division of Financial Institutions says, after Act 56 of 2021, "Can I still take out a payday loan? No. The new law prohibits payday loans."
- Rate caps, and we list no payday stores: Arkansas (rates capped at 17%), Colorado (rates capped at 36%), Connecticut (rates capped at 36%), Maryland (rates capped at 24%), Massachusetts (rates capped at 23%), Minnesota (rates capped at 50%), Montana (rates capped at 36%), Nebraska (rates capped at 36%), New Jersey (over 30% is criminal usury), New Mexico (rates capped at 36%), New York (over 25% is criminal usury), North Carolina (rates capped at 33%), Pennsylvania (capped at $9.50 per $100 a year), South Dakota (rates capped at 36%), Vermont (rates capped at 24%). Each state page names the law behind its cap.
What a payday loan costs
Payday fees look small but are large for the time you borrow. In Florida, for example, a single-payment payday loan can be at most $500, and fees cannot exceed 10% of the amount you receive (Fla. Stat. § 560.404(5), (6)(a)). In other states the limits are different, or there are none. Our guide to how APR works in payday and cash advance loans shows how to compare a fee with an annual rate, and installment loans vs. payday loans explains the other common option.
Options to consider first
These are general options, not recommendations of a particular provider:
- A credit union payday alternative loan (PAL). Federal credit unions may offer PALs. PALs I are $200 to $1,000, repaid over 1 to 6 months, and need one month of membership first. PALs II go up to $2,000 over 1 to 12 months, with no waiting period. The application fee is at most $20 (12 CFR 701.21(c)(7)). The NCUA says the rate can be up to 28% while its current 18% loan ceiling applies, which runs through September 10, 2027. Ask the credit union whether it accepts an ITIN for membership.
- A payment plan. Call the landlord, utility or medical office you owe, and ask for more time or a plan.
- Local help. Call 211 or visit 211.org to find local help with rent, utilities and food in many areas.
Frequently asked questions
Can I get a payday loan with no Social Security number?
Only from a lender that accepts another number, such as an ITIN, and where your state allows payday loans. Ask the lender first. If you have no number at all, a pawn loan or a bank or credit union account may not need one.
Does a payday lender have to accept my ITIN?
It is the lender's choice, within its state's rules. Some lenders accept an ITIN and others ask only for a Social Security number, so ask before you apply.
Can a lender ask about my immigration status?
Yes. Federal Regulation B lets a creditor consider immigration status and what it needs to know about repayment. The same rule forbids it from considering your national origin.
Can I open a bank account with an ITIN?
Federal rules let banks and credit unions verify a person who is not a U.S. person with an ITIN, a passport number or certain other government photo IDs. Each bank sets its own policy, so ask which documents it accepts.
Does getting an ITIN affect my immigration status?
The IRS says an ITIN does not provide or change immigration status and does not authorize work. For questions about your own case, ask an immigration attorney or a DOJ-accredited representative.
My ITIN expired. Can I still use it?
The IRS says ITINs can expire and explains how to renew one. Whether a lender accepts an expired number is up to the lender.
Are payday loans available in every state?
No. By our verified state rules, Georgia makes payday lending unlawful, Arizona and the District of Columbia no longer license payday lenders, the regulators in West Virginia and Hawaii say payday loans are prohibited, and 15 more states have rate caps under which we list no payday stores. That is 20 of the 50 states and DC. Check your state in the lender directory.
Sources
- Individual Taxpayer Identification Number, Internal Revenue Service, updated October 28, 2025.
- Texas Finance Code chapter 371, Pawnshops, Texas Legislature, checked October 9, 2026 (our state rules data).
- Understanding your CP565 notice, Internal Revenue Service, updated August 11, 2026.
- What is a payday loan?, Consumer Financial Protection Bureau, reviewed May 28, 2024.
- 12 CFR 1002.6, Rules concerning evaluation of applications (Regulation B), eCFR, checked October 11, 2026.
- 31 CFR 1020.220, Customer identification programs for banks, eCFR, checked October 11, 2026.
- 12 CFR 701.21, Loans to members (payday alternative loans), eCFR, checked October 11, 2026.
- Permissible Loan Interest Rate Ceiling Extended, National Credit Union Administration, February 2026.
- Fla. Stat. § 560.404, Requirements for deferred presentment transactions, Florida Legislature, checked October 11, 2026.
- Consumers, West Virginia Division of Financial Institutions, checked October 11, 2026.
- Consumer FAQ, Hawaii Division of Financial Institutions, checked October 11, 2026.
- State rules for Virginia, Washington, South Carolina, Georgia, Arizona and the District of Columbia: our lender directory state rules data, last checked October 9, 2026, with the law linked in the table above.
- 211.org, United Way Worldwide, checked October 11, 2026.
We are not a lender. This is general information, not legal, tax or immigration advice. Rules change; check your state's current rules and the lender's own disclosures before you borrow.
Keep reading
Can You Get More Than One Payday Loan?
Can you have more than one payday loan? State law and lender rules decide. Examples of one-at-a-time limits, waiting periods and databases. Not a lender.
How Much Can You Borrow With Cash Advance?
How much you can borrow with a cash advance depends on the product, the lender and state limits. Examples of state caps, and what to ask before you borrow.
Payday, Title and Installment Loans in Texas: Rules, Costs and Options
Payday and title loans are legal in Texas with no state fee cap, but 46 cities set limits. The rules, costs and license checks. Independent; not a lender.