Gambling Loan vs Personal Loan: Key Differences Explained
Understanding Lender Rules, Risks, and Compliant Alternatives for Borrowing
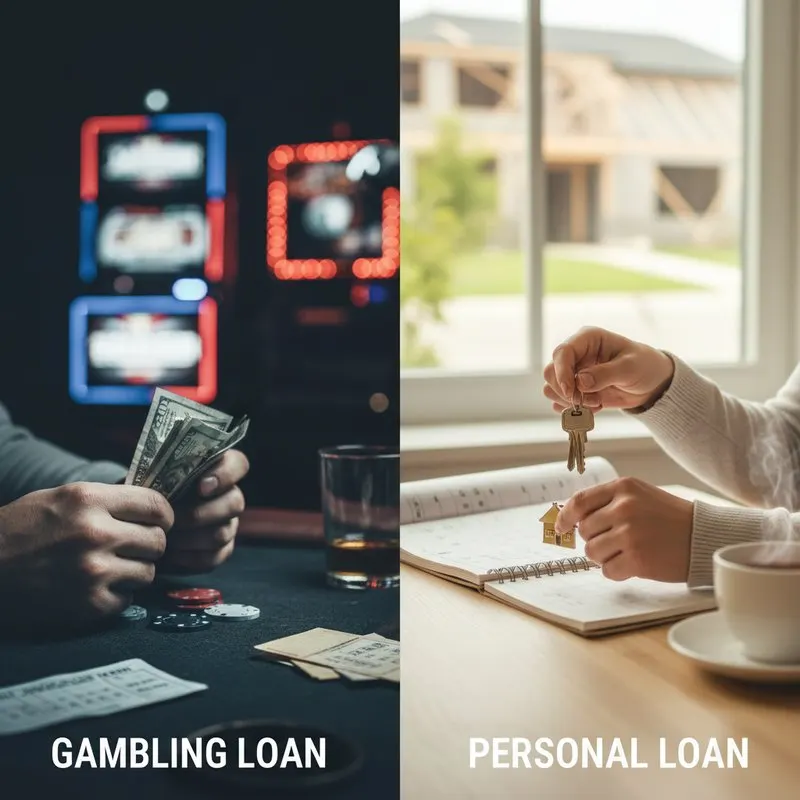
Quick Summary / Key Takeaways
- Many lenders restrict the use of personal loan funds for gambling in their terms. Lenders set their own rules, so read yours.
- “Gambling loan” is not a legal product category. The term usually points to high-cost loans, and borrowing for gambling carries real risk.
- The core difference lies in lender risk assessment; personal loans are usually meant for predictable expenses, while gambling is speculative and can put repayment at risk.
- Misrepresenting the purpose of a loan to fund gambling can break the loan agreement and may lead to default, collection and damage to your credit.
- For urgent, non-gambling cash needs, options such as credit union payday alternative loans are a better fit than misusing a personal loan.
Introduction
When you need to borrow money, the reason matters immensely to lenders. This is especially true when comparing a gambling loan vs personal loan. While a personal loan offers a flexible financial tool for predictable expenses like consolidating debt or renovating a kitchen, using it for gambling goes against the terms many lenders set. The core of the issue is risk—not just for you, but for the financial institution underwriting the loan. Understanding the key differences explained in this guide is crucial for making responsible financial decisions. Lenders structure personal loans based on a borrower’s stable ability to repay, an equation that speculative activities like gambling completely upend. This guide breaks down the personal loan gambling restrictions, compares borrowing rules, and clarifies why the distinction is so important for your financial health. Our lender directory lists licensed lenders by state.
Loan Use of Funds Comparison
| Feature | Standard Personal Loan | “Gambling Loan” (Specialty) | Short-Term Cash Advance |
|---|---|---|---|
| Permitted Uses | Set by the lender; often debt consolidation or home repair | Varies by lender | Varies by lender and state |
| Prohibited Uses | Set by the lender's terms; many restrict gambling | Varies by lender | Varies by lender and state |
| Lender Scrutiny | Varies by lender | Varies by lender | Varies by lender and state |
| Typical APR Range | Averaged 11.86% for 24-month loans in Q2 2026 (Federal Reserve) | Often much higher; a two-week payday loan at $15 per $100 is almost 400% APR (CFPB example) | Varies widely by state/lender |
Lender Restrictions & Risk Factors Comparison
| Factor | Mainstream Bank (Personal Loan) | Specialty/Payday Lender | Online Loan Marketplace |
|---|---|---|---|
| Stance on Gambling | Many terms restrict it; read yours | Varies by lender | Varies by lender |
| Credit Score Impact | Varies by lender | Varies by lender | Varies by lender |
| Repayment Terms | Varies by lender | Payday loans are usually due on the next payday (CFPB) | Varies by lender |
| Regulatory Oversight | Federal and state rules apply | Varies by state | Varies by state and lender |
Application Preparation Checklist
- Review your budget to confirm a genuine, non-gambling related cash shortfall.
- Check your credit report for inaccuracies that could hold up an application.
- Carefully read the “use of funds” section in any loan agreement before signing.
- Exhaust non-borrowing options first, such as savings or asking for help.
Post-Arrival Checklist
- Look at regulated options for true emergencies, such as a credit union payday alternative loan.
- Create a detailed repayment plan you can stick to before accepting any funds.
- Avoid any lender that is not transparent about its rates, fees, and terms.
- If borrowing is to cover losses, seek help from a credit or gambling counseling service.
Table of Contents
Section 1: Fundamental Differences
- What is the main difference between a gambling loan and a personal loan?
- Why do lenders prohibit using personal loans for gambling?
- Are ‘gambling loans’ from legitimate banks a real thing?
- How does the loan application process differ for these loan types?
Section 2: Risks, Rules, and Regulations
- What are the biggest risks of using any loan for gambling?
- What happens if you lie about the purpose of a personal loan and use it for gambling?
- How do interest rates and fees compare?
- Are there specific regulations governing loans for gambling purposes?
Section 3: Compliant Alternatives and Financial Health
- What are some compliant short-term alternatives to a personal loan for urgent cash needs?
- How can I get emergency cash without violating a loan’s terms of use?
- Can taking out a loan for gambling affect my credit score?
- Where can I find help if I’m borrowing money to cover gambling losses?
Frequently Asked Questions
Section 1: Fundamental Differences
FAQ 1: What is the main difference between a gambling loan and a personal loan?
The main difference is that a personal loan is a financial product whose contract often restricts use for gambling, whereas “gambling loan” is an informal term for high-cost borrowing used to gamble. Personal loans are underwritten on your ability to repay. Loans that people use to gamble, such as payday or title loans, can carry very high rates. For smaller emergency needs, see our guide to installment loans vs. payday loans.
FAQ 2: Why do lenders prohibit using personal loans for gambling?
Some lenders restrict using personal loans for gambling because it can raise the risk that you cannot repay. Lenders set their own rules and write them into the contract, so check yours. A lender usually looks at your income and your ability to make steady payments. Gambling is speculative and can quickly reduce what you have left to repay. A use-of-funds clause is one way a lender can try to manage that risk.
FAQ 3: Are ‘gambling loans’ from legitimate banks a real thing?
“Gambling loan” is an informal term, not a defined legal product. We are not aware of a mainstream bank or credit union that markets a loan for gambling. The term usually points to high-cost products such as payday or title loans, where lenders may not ask what the money is for. Our lender directory lists licensed lenders by state.
FAQ 4: How does the loan application process differ for these loan types?
The application process differs by lender and product. A personal loan application often involves a credit check, income verification (such as pay stubs or tax returns) and a stated purpose for the funds. Short-term, high-cost lenders may ask for less. Each lender sets its own steps, so ask what it requires before you apply. Under federal law, closed-end lenders must disclose the amount financed, finance charge, APR and total of payments (Regulation Z), so read those figures before you sign.
Section 2: Risks, Rules, and Regulations
FAQ 5: What are the biggest risks of using any loan for gambling?
The biggest risk of using any loan for gambling is entering a rapid debt cycle where you are chasing losses with borrowed money that accrues high interest. This creates a debt that is hard to escape, since you owe the loan plus interest whether you win or lose. Other major gambling loan risks include defaulting on the loan, damaging your credit, and potentially facing collection or legal action from the lender. It turns a pastime into a debt you still owe.
FAQ 6: What happens if you lie about the purpose of a personal loan and use it for gambling?
If you give a false purpose on a loan application, you may break the loan agreement, and a lender may treat it as a default. Many contracts let the lender demand the full balance if you break their terms; check yours. If you cannot pay, the lender can send the account to collections or sue. A lender can take money from your wages or bank account only after a court order, according to the CFPB. Unpaid debts and collections can appear on your credit report and make later borrowing harder. For legal questions, ask a licensed attorney or legal aid.
FAQ 7: How do interest rates and fees compare?
Interest rates and fees differ dramatically, reflecting the lender’s perceived risk. The Federal Reserve reported that 24-month personal loans at commercial banks averaged 11.86% in the second quarter of 2026 (G.19, released October 7, 2026). Credit card plans averaged 20.94% across all accounts and 22.15% on accounts assessed interest. Payday loans cost far more: the CFPB notes that a two-week loan at $15 per $100 works out to an APR of almost 400%. Your own rate depends on the lender, your credit and your state. See how APR works.
FAQ 8: Are there specific regulations governing loans for gambling purposes?
“Gambling loan” is not a legal category in the sources we cite. Rules generally follow the type of lender and the state. Payday and similar short-term lenders are governed largely by state law, which varies widely and often caps rates and fees. Whether a lender restricts the use of funds is set in its own contract. See where payday loans are legal and check your state regulator.
Section 3: Compliant Alternatives and Financial Health
FAQ 9: What are some compliant short-term alternatives to a personal loan for urgent cash needs?
Options for urgent, non-gambling cash needs include payday alternative loans (PALs) from federal credit unions, a payment plan with the biller, and local help through 211. Under NCUA rules, PALs I run $200 to $1,000 for 1 to 6 months, and PALs II go up to $2,000 for 1 to 12 months, with an application fee of no more than $20. The NCUA has extended the 18% federal credit union rate ceiling through September 10, 2027, and PALs may charge up to 28%. These are general options, not recommendations of a particular provider. Whichever you choose, use the money for the stated purpose.
FAQ 10: How can I get emergency cash without violating a loan’s terms of use?
To get emergency cash without breaking a loan’s terms, be honest about what the money is for and read the contract’s use-of-funds clause. For small, urgent expenses, some people choose a short-term loan rather than a large personal loan, but short-term loans can be costly. Compare the APR and total cost first, and ask the lender whether any use is restricted. Our lender directory lists licensed lenders by state.
FAQ 11: Can taking out a loan for gambling affect my credit score?
Yes, any loan can affect your credit, whatever you spend it on. Missed payments and collections can appear on your credit report and can lower your score. Applications can add credit inquiries, and more debt can raise how much of your available credit you use. Some lenders, such as payday lenders, may not report your payments at all, so on-time payments may not help you build credit (CFPB).
FAQ 12: Where can I find help if I’m borrowing money to cover gambling losses?
If you are borrowing money to cover gambling losses, consider reaching out to an organization that specializes in problem gambling and to a credit counselor. The National Council on Problem Gambling (NCPG) runs a national helpline; see its website for the current number and hours. A nonprofit credit counseling agency can help you build a budget or a debt management plan. The FTC warns that nonprofit status does not guarantee a service is free, affordable or legitimate, so check an agency with your state attorney general first, and note that a debt management plan can take 48 months or more.
Sources
- Consumer Credit G.19, Board of Governors of the Federal Reserve System, released October 7, 2026 (Q2 2026 rates).
- What is a payday loan?, Consumer Financial Protection Bureau, reviewed May 28, 2024.
- Can a payday lender garnish my bank account or my wages if I don't repay the loan?, Consumer Financial Protection Bureau, reviewed November 25, 2024.
- 12 CFR 1026.18, Content of disclosures (Regulation Z), Consumer Financial Protection Bureau, checked October 15, 2026.
- 12 CFR 701.21, Loans to members (payday alternative loans), eCFR, checked October 15, 2026.
- Permissible Loan Interest Rate Ceiling Extended, National Credit Union Administration, February 2026.
- How To Get Out of Debt, Federal Trade Commission, updated December 2025.
- 211.org, United Way Worldwide, checked October 15, 2026.
- National Council on Problem Gambling, nonprofit, checked October 15, 2026.
We are not a lender. This is general information, not financial or legal advice. Rules change; check your state's current rules and the lender's own disclosures before you borrow.
Keep reading
How to Get Cash Fast Without Ruining Your Credit A Clear Step by Step Guide
Options for getting cash quickly without hurting your credit, from credit union loans to payment plans. Independent; not a lender.
I Make $70K and Still Can’t Save — Here’s What’s Actually Going On (and What to Do)
Why a $70,000 salary can still leave nothing to save, and practical steps to find room in your budget. Independent; not a lender.
Gambling Loan vs Cash Advance: What to Know Before Borrowing
How borrowing to gamble differs from a credit card cash advance: purpose, costs, risks and lender rules to check first. Independent; not a lender.