Can You Get a Loan for a Wedding Ring? Financing Options Explained
Before you say ‘I do’ to a loan, understand the different ways to finance this significant purchase and what makes the most financial sense for your future.
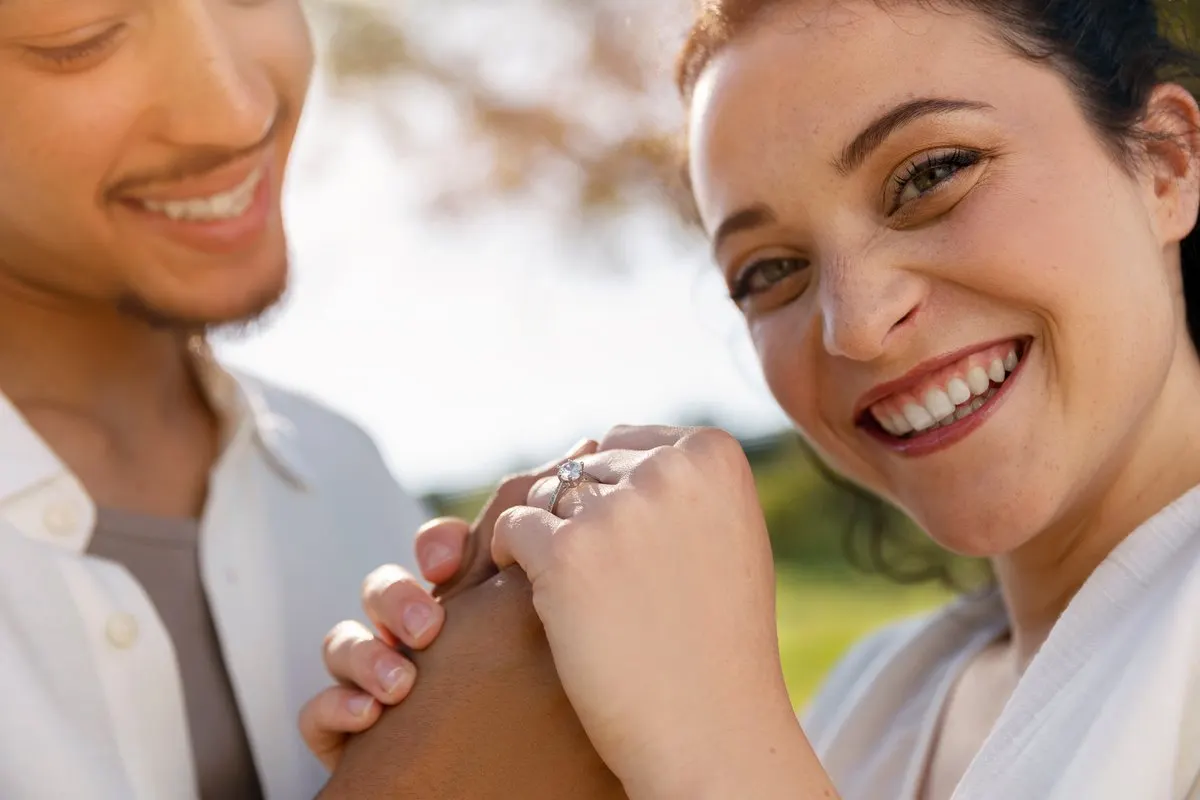
Quick Summary / Key Takeaways
- Yes, some lenders and sellers offer financing for a wedding ring, including personal loans, in-store jeweler financing, and credit cards. Each option has its own interest rates, terms, and credit requirements, so compare them.
- Personal loans often offer fixed monthly payments, and their rates can be lower than credit card rates (see the Federal Reserve averages in the Sources), making them a predictable way to manage the cost of a ring. They are unsecured, meaning you don’t need collateral.
- In-store financing may include 0% promotional periods. If the offer uses deferred interest and the balance isn’t paid in full by the end of the term, the CFPB says you can be charged the interest accrued from the date of purchase.
- Your credit score is a factor in the financing terms you are offered. Each lender sets its own cutoffs, so ask before you apply.
- Always consider alternatives to debt, such as saving up, choosing a less expensive ring (like one with a lab-grown diamond), or using a family heirloom. Borrowing less means lower payments.
Introduction
Yes, some lenders and sellers offer financing for a wedding ring. The real question isn’t *if* you can, but *how* you should and whether it’s the right financial decision for you. A ring can be a large expense, and some people finance it to avoid draining their savings. From traditional personal loans to in-store payment plans, a variety of wedding ring financing options are available to fit different budgets and credit profiles. This isn’t just about borrowing money; it’s about making a smart, informed choice that honors your commitment without creating long-term financial stress. The key is to understand the pros and cons of each method. A personal loan for a wedding ring offers a structured repayment plan with a fixed interest rate, making it easy to budget for. Jeweler financing might tempt you with a 0% interest period, but it can come with risks if you don’t pay it off in time. Navigating these choices requires a clear head and a bit of research. It’s about balancing the emotional desire for the perfect ring with the practical reality of your finances. Exploring your options is the first step, and for those looking to understand the landscape of short-term cash and financing possibilities, leading platforms provide a straightforward way to see what’s available without pressure. This guide will walk you through the different types of loans, what to watch out for, and how to choose the best path for your situation.
Engagement Ring Financing Comparison
| Financing Option | APR Range | Best For | Key Consideration |
|---|---|---|---|
| Personal Loan | Varies by lender | Predictable monthly payments over a set term. | Rates depend on your credit and income; ask each lender. |
| Jeweler Financing | 0% intro, then the rate in your agreement | Paying off the full amount during a 0% APR period. | Deferred interest may be charged back to the purchase date if not paid off in time (CFPB). |
| 0% APR Credit Card | 0% intro, then the rate in your card agreement | Earning rewards and short-term interest-free payments. | High interest accrues on the remaining balance after the intro period ends. |
| Buy Now, Pay Later (BNPL) | Varies by lender | Splitting the cost into a few smaller, immediate payments. | Terms are often short; read the repayment schedule and fees. |
Sample Monthly Payments for a $5,200 Ring (our example)
| Financing Method | Interest Rate (APR) | Loan Term | Estimated Monthly Payment |
|---|---|---|---|
| Personal Loan | 11% (example only) | 36 Months | ~$170 (our calculation) |
| 0% APR Card (Post-Intro) | Set by your card agreement | N/A (Revolving) | Varies (High Interest) |
| Jeweler Financing (Post-Intro) | Set by your agreement | N/A (Revolving) | Varies (Very High Interest) |
| Saving Up | 0% | 12 Months | ~$433/month saved |
Application Preparation Checklist
- Set a Realistic Budget: Determine what you can comfortably afford to spend without jeopardizing other financial goals.
- Check Your Credit Score: Know your credit standing before you apply.
- Research Ring Prices: Get a clear idea of the cost of the ring you want before seeking financing.
- Compare Lender Offers: Ask lenders whether prequalifying uses a soft credit check, then compare interest rates and terms.
Post-Arrival Checklist
- Set Up Automatic Payments: Ensure you never miss a payment, which can negatively affect your credit score.
- Pay More Than the Minimum: If possible, pay extra each month to reduce the total interest paid and shorten the loan term.
- Monitor Promotional Periods: If you used a 0% APR offer, mark the expiration date and aim to pay the balance before it ends.
- Refinance if Necessary: If your credit improves or better rates become available, consider refinancing to a lower-interest loan.
Table of Contents
Section 1: Core Financing Questions
- What are the most common ways to finance a wedding ring?
- What credit score is needed for wedding ring financing?
- Can you get a loan for a wedding ring with bad credit?
Section 2: Comparing Your Options
- How do personal loans for wedding rings work?
- Is in-store jeweler financing a good idea?
- What are the pros and cons of using a credit card for a ring?
Section 3: Alternatives and Best Practices
- What are some alternatives to taking out a loan for a ring?
- How can I create a realistic budget for a wedding ring?
Frequently Asked Questions
Section 1: Core Financing Questions
FAQ 1: What are the most common ways to finance a wedding ring?
Common ways to finance a ring include personal loans, in-store financing from the jeweler, and 0% APR credit cards. A personal loan gives you a lump sum with a set interest rate and monthly payments over a set term. In-store financing may feature promotional 0% interest periods, but some offers use deferred interest. A new credit card with a 0% introductory APR on purchases can also work if you pay off the ring before the promotional period ends. Some sellers also accept “Buy Now, Pay Later” services. Our lender directory lists licensed lenders by state at /lenders/.
FAQ 2: What credit score is needed for wedding ring financing?
Each lender sets its own credit requirements, and higher scores usually bring lower interest rates. Lenders view applicants with higher scores as lower risk and may reward them with better terms on personal loans and credit cards. Some jewelers and lenders may approve applicants with fair credit, but the rates are likely to be higher. Promotional 0% APR offers often require stronger credit; ask the seller or card issuer what it requires. Check your credit report and score before applying so you know where you stand.
FAQ 3: Can you get a loan for a wedding ring with bad credit?
Some lenders may offer financing to borrowers with bad credit, but options may be more limited and more expensive. Mainstream lenders and prime credit card issuers may decline your application. Lenders that focus on borrowers with poor credit may charge high rates and fees, so read the terms and the APR carefully. Some jewelers may offer layaway plans, which hold the ring while you pay over time; ask whether a credit check is required. Another path is to apply with a co-signer, but a co-signer becomes responsible for the debt. Be wary of anyone who promises a loan before checking your credit; the FTC says there is no loan and no lender in advance-fee scams.
Section 2: Comparing Your Options
FAQ 4: How do personal loans for wedding rings work?
A personal loan for a wedding ring is often an unsecured installment loan, meaning you may not need to provide collateral. You apply with a bank, credit union, or online lender, and if approved, you receive a lump sum to purchase the ring. You then repay it in fixed monthly installments over a set period. With a fixed rate, your payment amount stays the same, which makes it easier to budget. Approval and the rate depend on your credit and income. For comparison, the Federal Reserve reported an average APR of 11.86% on 24-month personal loans at commercial banks in Q2 2026, and 22.15% on credit card accounts assessed interest (G.19, October 7, 2026); your own rate may differ. Some lenders let you prequalify with a soft credit check; ask before you submit.
FAQ 5: Is in-store jeweler financing a good idea?
In-store jeweler financing can work, but only if you pay it off in time and understand the terms. The main appeal is a promotional 0% interest period, and its length varies by offer. The risk is deferred interest. The CFPB describes deferred-interest promotions as offers of no interest for a set period if the promotional balance is paid in full by the end, with accrued interest charged from the time of purchase if it is not. Read the agreement for the rate that applies after the promotion.
FAQ 6: What are the pros and cons of using a credit card for a ring?
Using a credit card offers convenience and may earn rewards like points or cash back. A new card with a 0% introductory APR can let you pay the ring off interest-free, but the length of the offer varies, and a high rate applies after it ends. If you carry a balance, interest can quickly raise the ring’s total cost. A large purchase can also increase your credit utilization, which may temporarily lower your credit score. It works best if you have a clear plan to pay off the balance before the offer ends.
Section 3: Alternatives and Best Practices
FAQ 7: What are some alternatives to taking out a loan for a ring?
One alternative to a loan is to save up and pay with cash, so you pay no interest. You could also ask about a layaway plan, where the jeweler holds the ring while you make payments over time. Another option is a more affordable ring, such as one with a lab-grown diamond or another gemstone. A family heirloom is a sentimental and low-cost choice. Spreading the cost over a set time through savings avoids new debt.
FAQ 8: How can I create a realistic budget for a wedding ring?
Creating a realistic budget starts with your actual income, expenses, and savings goals, not a rule of thumb like ‘three months’ salary.’ Decide on a total amount you feel comfortable spending without compromising your financial stability. Work backward from there. For example, if you want to buy a ring in one year, divide your target price by 12 to find your monthly savings goal. Track your spending for a month to see where you can cut back. Be open with your partner about finances and priorities.
Sources
- Consumer Financial Protection Bureau Encourages Retail Credit Card Companies to Consider More Transparent Promotions, Consumer Financial Protection Bureau, June 8, 2017.
- Consumer Credit - G.19, Terms of Credit, Board of Governors of the Federal Reserve System, release of October 7, 2026 (Q2 2026 data).
- What to know about advance-fee loans, Federal Trade Commission, July 2022.
We are not a lender. This is general information, not financial or legal advice. Rules change; check your state's current rules and the lender's own disclosures before you borrow.
Keep reading
Cash Advance Now: Fast Options When You Need Money Immediately
Need cash fast? What cash advances cost, how funding times vary, and cheaper options to try first. Independent; not a lender.
Cash Quick: Your Guide to Fast and Frictionless Funding Options
Need cash quickly? How funding times vary by product, what each option costs, and how to prepare an application. Independent; not a lender.
Best Ways to Get Cash Fast in 2026 Without Debt Traps
Ways to get cash quickly without a debt trap: what to check on fees, APR and due dates, and lower-cost options. Independent; not a lender.